









- Which customer acquisition channels will be affected by cross-border marketing trends in 2026?Sep 06, 2026View details
- Which homogenization risks should be considered in an analysis of the AI-powered website building industry?Aug 30, 2026View details
- How Will AI Marketing Trends 2026 Change Advertising Budget AllocationAug 28, 2026View details
- Is the EV SSL certificate market shrinking or upgrading? How should companies assess certificate procurement?Aug 11, 2026View details
- Why the old AMP SEO 2020 practices no longer work and what has changed in current optimization prioritiesAug 02, 2026View details
- How to Choose Topics for an Industry News Section to Attract More Organic Search TrafficJul 29, 2026View details
The EU Includes B2B Standalone Websites in EPR Carbon Footprint Reporting
Starting October 1, 2026, B2B foreign trade independent websites operated for EU customers will be brought within the scope of EU EPR-related regulation, making annual website carbon footprint reporting a new compliance requirement. For companies that rely on multilingual websites for customer acquisition, inquiry-based websites for handling business opportunities, and cross-border e-commerce stores for transactions, the key concern is not limited to the reporting action itself. The associated impact on search visibility, B2B platform rankings, and digital channel management also deserves attention.
The Scope of the New Regulation and Reporting Requirements Have Been Clarified
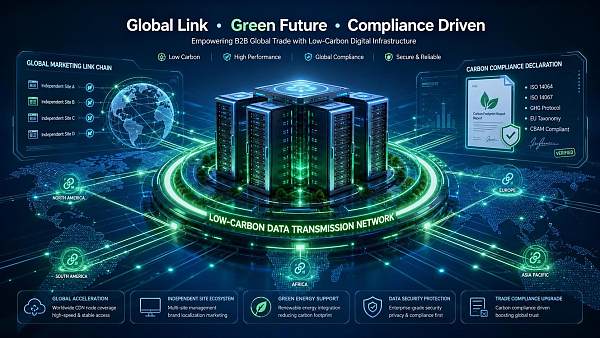
According to the information disclosed, on July 30, 2026, the European Commission updated the Digital Services Sustainability Regulation, bringing B2B foreign trade independent websites under the scope of extended producer responsibility (EPR) regulation for the first time. Starting October 1, 2026, independent websites operated for EU customers will be required to submit annual website carbon footprint reports through the EU EPR Portal.
The website types covered by this reporting requirement include multilingual corporate websites, inquiry-based websites, and cross-border e-commerce stores. The reports cover such aspects as server energy consumption, CDN data transmission, frontend rendering computing power, and third-party tracking scripts.
The confirmed consequences are also relatively direct: websites that fail to submit reports will be marked as “non-sustainable digital channels,” affecting the display of green labels in Google Search Console and priority rankings on B2B procurement platforms such as EUROPAGES and Kompass.
The Impact Extends Beyond Website Development
Foreign Trade Companies Targeting EU Customer Acquisition Need to Reassess Their Website Compliance Boundaries
From an industry perspective, trading companies conducting business directly with EU customers will be the first to feel the change. This is because their independent websites serve both as brand showcases and as entry points for inquiries and leads. Once marked as “non-sustainable digital channels,” the main impacts will fall on customer acquisition efficiency, platform exposure, and customers’ initial trust assessment. The more pressing issue at present is that companies need to clarify which websites, language versions, EU-market-facing pages, or business units should be included in the reporting scope.
Digital Operations Teams at Manufacturing Companies and Brand Owners Will Handle More Data Organization
For processing and manufacturing companies and businesses taking their own brands overseas, the impact will not be limited to the marketing department. Since the reporting content involves server energy consumption, CDN data transmission, frontend rendering computing power, and third-party tracking scripts, collaboration among website operations, technical teams, and compliance functions will become closer. The business areas requiring attention will focus more on reviewing website infrastructure, managing third-party tool lists, and preparing the basis and scope for annual reports.
Digital Service Providers and Supply Chain Support Companies May Be Asked by Customers to Provide Supporting Materials
Based on current observations, supply chain service companies that provide website development, hosting, CDN, data analytics, and tracking script deployment services may also be brought into the coordination process because of customer reporting needs. Although the available information does not extend to defining service provider responsibilities, in actual business operations customers will likely pay greater attention to whether service configurations, script calls, and transmission-related materials can be clearly explained. This will directly affect the efficiency of their reporting preparations.
The Ranking Logic of B2B Procurement and Channel Platforms Deserves Continued Attention
For companies that rely on platforms such as EUROPAGES and Kompass for exposure, the impact will also appear in off-site channels. Existing information has already indicated that failure to report will affect the priority rankings on these platforms. This suggests that website carbon footprint reporting will no longer be merely a back-office compliance action and may also begin to influence the distribution results of digital channels.
Which Practical Issues Should Companies Focus on Now?
First Confirm the Scope of Websites “Operated for EU Customers”
The first issue companies need to address is not a general discussion of green compliance, but the identification of internal website boundaries. Multilingual corporate websites, inquiry-based websites, and cross-border e-commerce stores are all included in the known scope. In actual management, companies should first confirm which websites and sub-sites, as well as which business pages targeting EU customers, need to be included in the preparation for annual reporting.
Organize the Technical and Tool-Related Items Involved in Reporting as Soon as Possible
Since the reporting dimensions have been clearly defined to include server energy consumption, CDN data transmission, frontend rendering computing power, and third-party tracking scripts, companies need to establish a list of website technical resources in advance. The focus is not on extrapolating additional standards, but on taking stock of the elements already known to be included in the reporting, so as to avoid having to supplement materials only when the reporting deadline is approaching.
Include the Impact on Search Visibility and Platform Rankings in Business Assessments
What deserves greater attention at present is that the impact of failing to report is not limited to compliance records. Changes in the display of green labels in Google Search Console and in the priority rankings on B2B procurement platforms mean that marketing, sales, and operations teams need to jointly assess potential fluctuations in lead generation caused by changes in website status, while reserving room for communication and adjustments.
Continue Tracking Official Statements and Implementation Details
The analysis indicates that this regulation has provided a clear direction for reporting, but at the implementation level, companies should continue to verify subsequent official statements, particularly whether the reporting scope, annual cycle, document formats, and platform operating requirements are further clarified. For companies that rely on the EU market, these implementation details will directly affect the pace of internal preparations.
This Appears to Be an Early Extension of Digital Compliance
The key significance of this development is that the points of contact for the EU’s sustainability requirements have extended from physical products and supply chain responsibilities to the digital channels of B2B companies themselves. Websites are no longer merely marketing assets; they are also beginning to be treated as compliance objects that can be reported, marked, and affected by ranking mechanisms.
However, based on the information currently available, this change is better understood as both an implemented regulatory action and an industry signal that still requires further observation. On the one hand, clear information is available regarding the reporting requirements, covered entities, and consequences of failing to report. On the other hand, the industry still needs to continue tracking the implementation scope, the depth of company preparations, and how the various platforms will present the relevant information going forward.
In the Short Term It Is a Reporting Requirement; in the Long Term It Is a Change in Channel Management Logic
Overall, this development should not be understood merely as a newly added form-filling task. It indicates that independent websites operated for the EU market by foreign trade companies, manufacturing companies, and participants in the digital services chain are entering a more detailed sustainability regulatory framework.
From a rational perspective, the short-term impact of this change will first be reflected in compliance reporting pressure and material preparation requirements. In the longer term, it may also signal that companies need to re-examine their website architecture, use of tracking tools, and digital channel operations. At present, it is more appropriate to understand this as both an already effective regulatory change and an industry development requiring continued observation of implementation details and platform feedback.
Basis of This Article and Directions for Further Verification
This article was generated based on the information title, event date, and event summary provided by the user. Its core basis includes the background to the update of the Digital Services Sustainability Regulation, the implementation date of October 1, 2026, the annual website carbon footprint reporting requirement through the EU EPR Portal, and the described impact of failure to report on the display of green labels in Google Search Console and priority rankings on B2B procurement platforms.
This type of information usually also requires continuous cross-verification against official announcements, regulatory documents, corporate announcements, industry association information, authoritative media reports, and documents issued by standards organizations. Since no specific official source links were provided in the input, this article cannot further verify the text of the original links. The relevant implementation details still require continued observation, with particular attention to subsequent official explanations, whether the reporting scope is further refined, and whether the specific display rules on the platform side are further clarified.
Related Articles


Related Products
 Yiyingbao SaaS Intelligent Website Building and Marketing SystemYiyingbao SaaS Intelligent Website Building and Marketing System, AI-powered no-code website building, rapid creation of multilingual B2B international websites in 10 minutes, global server acceleration, AI-powered SEO optimization, helping businesses connect efficiently with global markets. The perfect integration of technology and operation makes building an international trade website remarkably simple
 AI+SEM Intelligent Advertising Marketing SystemAI+SEM drives intelligent ad creation, empowering full-funnel precision advertising marketing. The system automatically generates weekly/monthly reports, AI recommends keywords and target countries, monitors core metrics in real-time with intelligent alerts, and enables one-click high-conversion ad solutions to help quickly acquire customers and improve ROI.
 AI+SEO Dual-Engine System Optimization ServicesYiyingbao’s AI+SEO dual-engine optimization system helps foreign trade enterprises acquire high-quality organic traffic through AI-powered keyword research, content generation, and comprehensive technical optimization, significantly improving search rankings and conversion rates.
 AI+SNS Social Media Marketing SystemYingbao AI+SNS Social Media Marketing System - Precision social capture for the social media era. Supports one-click content synchronization across major platforms like Facebook and LinkedIn. AI intelligently rewrites posts for enhanced relevance. 24/7 AI customer service and user profiling analysis empower businesses to efficiently expand into global markets.
 AI+SEO营销解决方案易营宝AI+SEO营销解决方案,通过AI批量写作、智能生成TDK、精准关键词扩词等功能,全面优化网站SEO效果,提升流量与转化率。助力企业构建高效智能网站新生态。
 AI+SEM Advertising Marketing SolutionsAI+SEM Advertising Marketing Solution leverages AI technology to deeply empower SEM ad campaigns. It automatically generates weekly/monthly reports using AI, presenting account data across multiple dimensions for comprehensive insights into campaign performance and trends. The system precisely recommends keywords and target countries, intelligently generates high-conversion ad copy, and enables one-click activation of efficient campaign plans to help businesses rapidly acquire customers. Simultaneously, it monitors core metrics in real time, intelligently identifies abnormal fluctuations, and issues timely alerts to ensure stable, high-return advertising results.
 Domain Name ServicesEasyWin provides professional domain name services, including intelligent queries, one-stop registration, brand protection, and full lifecycle management, helping businesses build a digital brand image.
 EasyOperate B2C Cross-Border E-Commerce Platform & Independent WebsiteEasyStore B2C Cross-border E-commerce Independent Store is an intelligent website building and cross-border e-commerce integrated solution independently developed by EasyStore Information Technology (Beijing) Co., Ltd. The system is specially designed for small and medium-sized as well as large export enterprises, integrating 'website building, operation, marketing, advertising, and conversion' into one, helping enterprises quickly establish cross-border e-commerce independent stores to achieve brand globalization and global sales growth.
The platform supports multiple languages, multiple currencies, and multi-channel marketing, with built-in AI intelligent translation and SEO optimization systems, suitable for mainstream markets such as Southeast Asia, Europe and America, Latin America, and the Middle East, assisting Chinese manufacturing enterprises in efficiently deploying international e-commerce strategies. SSL证书易营宝提供专业SSL安全证书服务,包括单域名和泛域名证书,确保网站数据传输加密、身份验证和完整性保护,助力企业建立安全可信的在线业务环境。









