- Which customer acquisition channels will be affected by cross-border marketing trends in 2026?Sep 06, 2026View details
- Which homogenization risks should be considered in an analysis of the AI-powered website building industry?Aug 30, 2026View details
- How Will AI Marketing Trends 2026 Change Advertising Budget AllocationAug 28, 2026View details
- Is the EV SSL certificate market shrinking or upgrading? How should companies assess certificate procurement?Aug 11, 2026View details
- Why the old AMP SEO 2020 practices no longer work and what has changed in current optimization prioritiesAug 02, 2026View details
- How to Choose Topics for an Industry News Section to Attract More Organic Search TrafficJul 29, 2026View details
Which areas should be reviewed when the cost of acquiring customers for export business increases?
When customer acquisition costs rise, do not rush to cut the budget. With the same total investment, clicks may have become more expensive, but there may also be more invalid visits, landing-page drop-off, gaps in sales follow-up, or expenses that should not be included may have been included in customer acquisition costs. Only by breaking down “rising costs” into verifiable stages can you determine whether to pause, adjust, or retain a channel.
First, standardize the calculation scope for customer acquisition costs
Many reports simply divide advertising spend by the number of form submissions. While the resulting figure may seem straightforward, it is insufficient for budget decisions. Qualified leads in export business differ significantly from ordinary visits: some inquiries only request a catalog, some come from countries not covered, and some do not match in product specifications, minimum order quantity, or payment terms. If all of these are counted as leads, a channel may appear inexpensive while the sales team continues to spend time on them.
It is recommended to retain three levels of measurement at the same time: cost per visit, cost per raw lead, and cost per qualified opportunity. Qualified opportunities should have clear criteria, such as verifiable contact information, demand that matches the main products, a serviceable region, and purchase intent that has entered the communication stage. Different channels do not need to pursue the same cost per form submission, but the differences should be compared after applying the same qualified-opportunity criteria.
It is also necessary to verify whether cost allocation is consistent. Creative production, page development, translation, localized materials, sales tool subscriptions, agency service fees, and advertising spend should not be included at times and excluded at others. A one-time website-building investment should not all be charged to a single month either, otherwise short-term customer acquisition costs will be abnormally inflated. Management reports can present media spend and total customer acquisition investment separately to avoid mistaking operational issues for advertising issues.
When traffic becomes more expensive, first check whether quality has changed as well
An increase in cost per click does not automatically mean that a channel has become ineffective. Intensified competition in the target market, keyword coverage that is closer to purchase intent, and changes in ad placement can all increase the price per click. Cost changes need to be viewed together with post-visit behavior: visit duration, views of key pages, file downloads, inquiry initiation, form submissions, and contactability after submission are more informative than clicks alone.
When clicks increase but time spent on product pages is very short, first investigate search terms, audience targeting, and targeting regions. Traffic generated by broad match often includes job seekers, repair-related searches, learning materials, small retail orders, or irrelevant needs with names similar to the product. Social channels can also generate engagement without inquiries when interest labels are too broad. If a type of traffic has high visit volume but few inquiries, it should not be handled solely by lowering bids; it should be separately monitored in subsequent budgets.
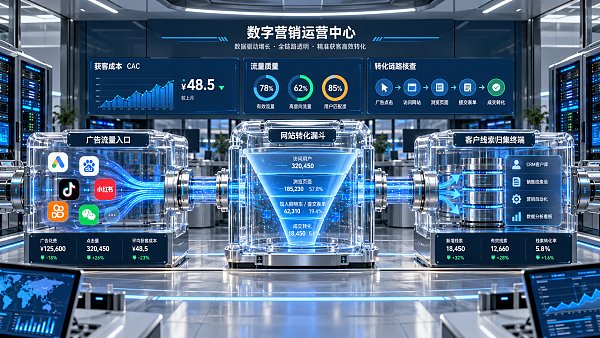
Attention should also be paid to device and regional combinations. If the share of mobile clicks suddenly rises, but specification tables, certification documents, or inquiry fields on the page are difficult to read on small screens, this can result in “normal visits but declining conversions.” In some regions, slow network access, incomplete multilingual content, or the inability to provide commonly used local contact options can also cause visitors with purchasing intent to leave at the page stage.
Landing-page losses are often masked by advertising data
The product, application, or delivery conditions promised in ad copy must be addressed quickly in the first screen of the landing page. A visitor searching for “corrosion-resistant fittings for a certain material” may instead first see a broad company introduction and need to navigate through multiple layers before confirming the material, size range, processing method, and application scenarios. This often reduces the inquiry rate. B2B pages do not need to be filled with promotional language, but they do need to enable visitors to quickly determine whether it is worthwhile to continue the conversation.
During review, go through the inquiry path in practice: whether loading is stable; whether multilingual versions contain untranslated fields; whether product materials can be downloaded; whether the form displays required-field errors; whether email notifications go to the spam folder; and whether phone, email, and instant communication options are available. Form fields should also match the value of the inquiry. With too few fields, sales staff need to repeatedly request additional information; with too many fields, first-time visitors may abandon submission. For products with complex specifications, prioritize collecting the product model, application, quantity range, and destination, and leave technical details for subsequent communication.
Although inquiries may decline in both cases, attribution issues and follow-up issues are entirely different
If the number of form submissions has not changed significantly but the proportion identified as qualified opportunities has declined, first check whether invalidation reasons in sales records are classified consistently. No budget, unsupported regions, mismatched needs, duplicate inquiries, and inability to make contact should be recorded separately. If all invalid leads are labeled as “invalid,” the advertising team cannot know which conditions to tighten, and the page team cannot determine which explanations need to be added.
Attribution is also easily affected by cross-device use, multiple visits, and offline communication. A visitor may first learn about a product through organic search and submit an inquiry days later after clicking a remarketing ad; they may also enter the website through social content and contact the company by email instead. Assigning all credit to the last click overestimates conversion-closing channels and underestimates early-stage content and organic traffic. At a minimum, retain the first source, most recent source, landing page, submission time, and subsequent status, and conduct periodic reviews rather than looking only at the day’s backend data.
When cost breakdowns and internal project accounting are involved, the classification approach reflected in materials such as Research on Tax Planning Issues of Power Grid Enterprises can also provide reference: first clarify cost ownership, allocation basis, and traceable supporting documents, and then discuss whether a specific investment should continue to increase. The key here is not to apply industry conclusions directly, but to avoid making budget decisions based on inconsistent criteria.
Channels cannot be compared solely by their apparent unit costs
The review cycle should also correspond to the business cycle. The value of inquiries involving high order values, customization, sampling, or technical confirmation cannot be judged solely on the day they are submitted; quality issues in leads for standardized products should become apparent more quickly. By connecting channels, pages, inquiry status, and subsequent transaction information, the source of rising costs will usually shift from “insufficient budget” to a specific, correctable stage.
Related Articles
Related Products
 Yiyingbao SaaS Intelligent Website Building and Marketing SystemYiyingbao SaaS Intelligent Website Building and Marketing System, AI-powered no-code website building, rapid creation of multilingual B2B international websites in 10 minutes, global server acceleration, AI-powered SEO optimization, helping businesses connect efficiently with global markets. The perfect integration of technology and operation makes building an international trade website remarkably simple
 AI+SEM Intelligent Advertising Marketing SystemAI+SEM drives intelligent ad creation, empowering full-funnel precision advertising marketing. The system automatically generates weekly/monthly reports, AI recommends keywords and target countries, monitors core metrics in real-time with intelligent alerts, and enables one-click high-conversion ad solutions to help quickly acquire customers and improve ROI.
 AI+SEO Dual-Engine System Optimization ServicesYiyingbao’s AI+SEO dual-engine optimization system helps foreign trade enterprises acquire high-quality organic traffic through AI-powered keyword research, content generation, and comprehensive technical optimization, significantly improving search rankings and conversion rates.
 AI+SNS Social Media Marketing SystemYingbao AI+SNS Social Media Marketing System - Precision social capture for the social media era. Supports one-click content synchronization across major platforms like Facebook and LinkedIn. AI intelligently rewrites posts for enhanced relevance. 24/7 AI customer service and user profiling analysis empower businesses to efficiently expand into global markets.
 AI+SEO营销解决方案易营宝AI+SEO营销解决方案,通过AI批量写作、智能生成TDK、精准关键词扩词等功能,全面优化网站SEO效果,提升流量与转化率。助力企业构建高效智能网站新生态。
 AI+SEM Advertising Marketing SolutionsAI+SEM Advertising Marketing Solution leverages AI technology to deeply empower SEM ad campaigns. It automatically generates weekly/monthly reports using AI, presenting account data across multiple dimensions for comprehensive insights into campaign performance and trends. The system precisely recommends keywords and target countries, intelligently generates high-conversion ad copy, and enables one-click activation of efficient campaign plans to help businesses rapidly acquire customers. Simultaneously, it monitors core metrics in real time, intelligently identifies abnormal fluctuations, and issues timely alerts to ensure stable, high-return advertising results.
 Domain Name ServicesEasyWin provides professional domain name services, including intelligent queries, one-stop registration, brand protection, and full lifecycle management, helping businesses build a digital brand image.
 EasyOperate B2C Cross-Border E-Commerce Platform & Independent WebsiteEasyStore B2C Cross-border E-commerce Independent Store is an intelligent website building and cross-border e-commerce integrated solution independently developed by EasyStore Information Technology (Beijing) Co., Ltd. The system is specially designed for small and medium-sized as well as large export enterprises, integrating 'website building, operation, marketing, advertising, and conversion' into one, helping enterprises quickly establish cross-border e-commerce independent stores to achieve brand globalization and global sales growth.
The platform supports multiple languages, multiple currencies, and multi-channel marketing, with built-in AI intelligent translation and SEO optimization systems, suitable for mainstream markets such as Southeast Asia, Europe and America, Latin America, and the Middle East, assisting Chinese manufacturing enterprises in efficiently deploying international e-commerce strategies. SSL证书易营宝提供专业SSL安全证书服务,包括单域名和泛域名证书,确保网站数据传输加密、身份验证和完整性保护,助力企业建立安全可信的在线业务环境。