









- Which customer acquisition channels will be affected by cross-border marketing trends in 2026?Sep 06, 2026View details
- Which homogenization risks should be considered in an analysis of the AI-powered website building industry?Aug 30, 2026View details
- How Will AI Marketing Trends 2026 Change Advertising Budget AllocationAug 28, 2026View details
- Is the EV SSL certificate market shrinking or upgrading? How should companies assess certificate procurement?Aug 11, 2026View details
- Why the old AMP SEO 2020 practices no longer work and what has changed in current optimization prioritiesAug 02, 2026View details
- How to Choose Topics for an Industry News Section to Attract More Organic Search TrafficJul 29, 2026View details
- Digital Marketing Shenzhen Market Insights: Why Are Companies Expanding Overseas Looking for Growth Teams in Shenzhen?Jul 31, 2026View details
- Can Zhejiang foreign trade independent websites still be developed today? Look at changes in traffic and lead generationJul 28, 2026View details
Shanghai–Rotterdam freight rates fall below USD 1,200/TEU
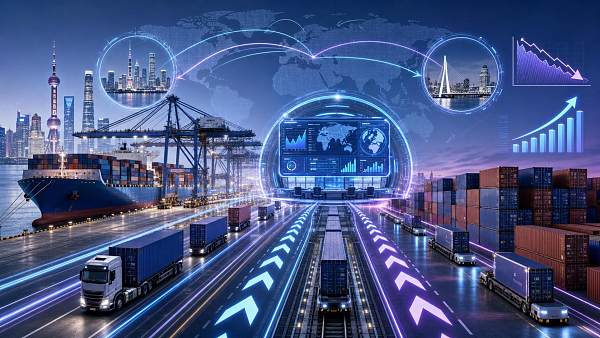
On August 1, 2026, the latest freight rates and capacity changes on the Shanghai–Rotterdam trunk route attracted widespread attention across foreign trade, manufacturing, cross-border e-commerce, and supply chain services. According to the latest weekly report from Drewry, spot freight rates on this core route have fallen below USD 1,200/TEU, while shipping companies have increased capacity allocations since August for small- and medium-volume, high-frequency B2B orders. For the industry, this concerns not only ocean freight costs themselves, but also directly affects delivery schedules, order-taking strategies, and the conversion efficiency of small-order business.
Confirmed Information on This Round of Freight Rate and Capacity Adjustments
According to the information provided, in the first week of August 2026, spot freight rates on the Shanghai–Rotterdam trunk route fell to USD 1,185/TEU, the lowest level since 2023. This downward movement was reported in Drewry’s latest weekly report.
During the same period, shipping companies announced that they would release an additional 35% capacity allocation from August, focusing on small- and medium-volume, high-frequency B2B orders. Confirmed information also indicates that this change will help foreign trade companies shorten delivery times, reduce logistics costs, and support the conversion rate of small orders placed through independent websites.
Which Business Areas Will Feel the Impact More Directly
Foreign Trade Order-Taking Teams Are More Concerned with Delivery Times and Pricing Flexibility
Analysis indicates that foreign trade companies serving overseas customers directly will feel the impact of this change relatively early. Falling freight rates will affect the cost structure of export quotations, while increased capacity may improve shipment arrangements, particularly for orders with smaller volumes and higher shipping frequencies. At present, these companies need to focus more on whether lower freight rates and released capacity can be delivered consistently in actual booking and shipment operations.
Manufacturing and Processing Companies Place Greater Emphasis on Production Scheduling and Shipment Timing
From an industry perspective, the main impact on processing and manufacturing companies will be reflected in delivery schedules. If the released capacity can accommodate small- and medium-volume orders, companies will have greater flexibility in production scheduling, split shipments, and delivery commitments. The key issue to monitor is whether the additional capacity is genuinely suited to their order frequency and whether improvements in logistics are sufficient to support tighter delivery arrangements.
Cross-Border Independent Websites and Small-Order Businesses Attach Greater Importance to Conversion Efficiency
Independent website-related businesses warrant attention because the information provided clearly indicates that small-order conversion rates may benefit from this development. For business models dependent on small-volume, high-frequency fulfillment, lower ocean freight costs and increased capacity may improve customers’ expectations regarding delivery speed and fulfillment reliability. Such businesses need to continue monitoring whether the actual logistics experience improves in line with the cost changes.
Supply Chain Service Providers Need to Reassess Their Service Mix
For freight forwarders, supply chain coordinators, and related service providers, this change may lead to adjustments in the structure of customer demand. If small- and medium-volume, high-frequency orders increase, service providers will need to refine booking arrangements, shipment schedule communications, and customer solution design. The key point to watch is whether market demand will shift from simply reducing freight costs toward placing greater emphasis on frequency, flexibility, and delivery coordination.
What Should Be Monitored More Closely in Current Operations
First Distinguish Announced Capacity Releases from Actually Available Capacity
Analysis indicates that the shipping companies’ announcement of an additional 35% capacity allocation is a clear signal, but companies still need to verify the actual bookable capacity at the execution level. For business teams, an increase in supply announced publicly does not mean that every type of cargo or every order batch will receive the same level of convenience at the same time.
Focus on Fulfillment Arrangements for Small- and Medium-Volume Orders
Since the additional capacity is primarily intended for small- and medium-volume, high-frequency B2B orders, relevant companies should first review their order structures and identify which customers and shipping schedules are most likely to benefit. In particular, businesses handling multiple small orders in parallel need to evaluate capacity changes together with delivery commitments and split-shipment arrangements.
Pricing Strategies Should Consider Costs and Delivery Times Simultaneously
Falling freight rates will directly affect export pricing logic, but companies should not focus solely on cost reductions. They should also assess whether improved delivery times can be converted into more competitive delivery terms. In business scenarios requiring rapid order confirmation, delivery expectations and logistics stability are often equally important.
Customer Communications Should Avoid Presenting a Temporary Change as a Long-Term Result
From an observational perspective, companies should communicate the sustainability of this change cautiously. Whether promising customers lower logistics costs or emphasizing faster delivery cycles, they need to base such statements on currently executable conditions rather than interpreting a single week’s freight rates and a temporary capacity release as a long-term norm.
This Information Appears to Represent a Temporary Market Window
Editor’s observation: Based on the information currently available, the core message conveyed by this development is that the main European route experienced a relatively significant decline in freight rates in early August 2026, while the supply side provided more proactive capacity arrangements for small- and medium-volume, high-frequency orders. This has practical reference value for foreign trade and cross-border businesses that depend on flexible fulfillment.
From an observational perspective, however, this change is better understood as a temporary market signal rather than an established long-term stable result. The reason is that what has currently been confirmed is the spot freight rate at a specific point in time and the capacity release arrangement beginning in August. How long this combination will last and whether its impact will extend to a broader range of order types still require continued monitoring.
The Industry Implications Are Moving into the Execution Stage
Overall, the value of this information lies not only in “lower freight rates,” but also in bringing costs, capacity, and order structure back into the same business framework. For foreign trade companies, manufacturers, and supply chain service providers, it is currently more appropriate to view this as a window for optimizing small-order and high-frequency shipment arrangements, rather than drawing premature conclusions about subsequent market trends.
Basis of This Article and Directions for Further Verification
This article was generated based on the information title, event date, and event summary provided by the user. The key references include the event date of August 1, 2026, and information concerning spot freight rates on the Shanghai–Rotterdam route and the capacity release beginning in August, as covered in Drewry’s latest weekly report.
For this type of industry information, subsequent verification would normally need to incorporate official announcements, company announcements, industry association information, authoritative media reports, and relevant business documents. Since no specific official source link was provided in the input, this article cannot further verify the content of the original link. Continued attention should be paid to whether freight rate changes persist, how the additional capacity is actually implemented, and how it affects the fulfillment of small- and medium-volume, high-frequency B2B orders.
Related Articles
Related Products
 Yiyingbao SaaS Intelligent Website Building and Marketing SystemYiyingbao SaaS Intelligent Website Building and Marketing System, AI-powered no-code website building, rapid creation of multilingual B2B international websites in 10 minutes, global server acceleration, AI-powered SEO optimization, helping businesses connect efficiently with global markets. The perfect integration of technology and operation makes building an international trade website remarkably simple
 AI+SEM Intelligent Advertising Marketing SystemAI+SEM drives intelligent ad creation, empowering full-funnel precision advertising marketing. The system automatically generates weekly/monthly reports, AI recommends keywords and target countries, monitors core metrics in real-time with intelligent alerts, and enables one-click high-conversion ad solutions to help quickly acquire customers and improve ROI.
 AI+SEO Dual-Engine System Optimization ServicesYiyingbao’s AI+SEO dual-engine optimization system helps foreign trade enterprises acquire high-quality organic traffic through AI-powered keyword research, content generation, and comprehensive technical optimization, significantly improving search rankings and conversion rates.
 AI+SNS Social Media Marketing SystemYingbao AI+SNS Social Media Marketing System - Precision social capture for the social media era. Supports one-click content synchronization across major platforms like Facebook and LinkedIn. AI intelligently rewrites posts for enhanced relevance. 24/7 AI customer service and user profiling analysis empower businesses to efficiently expand into global markets.
 AI+SEO营销解决方案易营宝AI+SEO营销解决方案,通过AI批量写作、智能生成TDK、精准关键词扩词等功能,全面优化网站SEO效果,提升流量与转化率。助力企业构建高效智能网站新生态。
 AI+SEM Advertising Marketing SolutionsAI+SEM Advertising Marketing Solution leverages AI technology to deeply empower SEM ad campaigns. It automatically generates weekly/monthly reports using AI, presenting account data across multiple dimensions for comprehensive insights into campaign performance and trends. The system precisely recommends keywords and target countries, intelligently generates high-conversion ad copy, and enables one-click activation of efficient campaign plans to help businesses rapidly acquire customers. Simultaneously, it monitors core metrics in real time, intelligently identifies abnormal fluctuations, and issues timely alerts to ensure stable, high-return advertising results.
 Domain Name ServicesEasyWin provides professional domain name services, including intelligent queries, one-stop registration, brand protection, and full lifecycle management, helping businesses build a digital brand image.
 EasyOperate B2C Cross-Border E-Commerce Platform & Independent WebsiteEasyStore B2C Cross-border E-commerce Independent Store is an intelligent website building and cross-border e-commerce integrated solution independently developed by EasyStore Information Technology (Beijing) Co., Ltd. The system is specially designed for small and medium-sized as well as large export enterprises, integrating 'website building, operation, marketing, advertising, and conversion' into one, helping enterprises quickly establish cross-border e-commerce independent stores to achieve brand globalization and global sales growth.
The platform supports multiple languages, multiple currencies, and multi-channel marketing, with built-in AI intelligent translation and SEO optimization systems, suitable for mainstream markets such as Southeast Asia, Europe and America, Latin America, and the Middle East, assisting Chinese manufacturing enterprises in efficiently deploying international e-commerce strategies. SSL证书易营宝提供专业SSL安全证书服务,包括单域名和泛域名证书,确保网站数据传输加密、身份验证和完整性保护,助力企业建立安全可信的在线业务环境。









