









- Which customer acquisition channels will be affected by cross-border marketing trends in 2026?Sep 06, 2026View details
- Which homogenization risks should be considered in an analysis of the AI-powered website building industry?Aug 30, 2026View details
- How Will AI Marketing Trends 2026 Change Advertising Budget AllocationAug 28, 2026View details
- Is the EV SSL certificate market shrinking or upgrading? How should companies assess certificate procurement?Aug 11, 2026View details
- Why the old AMP SEO 2020 practices no longer work and what has changed in current optimization prioritiesAug 02, 2026View details
- How to Choose Topics for an Industry News Section to Attract More Organic Search TrafficJul 29, 2026View details
How to integrate cross-border e-commerce payments? Key points for integrating PayPal, credit cards, and local payments.
Cross-border e-commerce payment integration: what determines conversion path first is not the number of interfaces
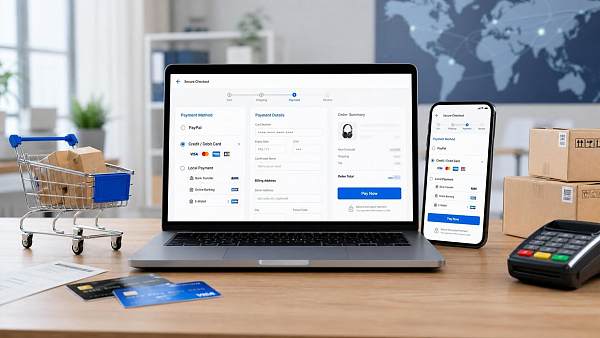
How to do cross-border e-commerce payment integration? On the surface, it looks like integrating PayPal, credit cards, and local payment methods. In reality, what is affected is whether visitors can complete payment smoothly, as well as whether subsequent settlement, refunds, and risk control remain stable.
In a website and marketing service integrated scenario, payment is not an isolated module. Traffic enters the store from Google search, ad landing pages, and social media referrals, and whether it can ultimately convert often comes down to this payment step.
Especially when building an overseas independent site, users in different regions have very different levels of trust in payment methods. If cross-border e-commerce payment integration is chosen only from the perspective of technical convenience, the conversion rate is usually not ideal.
A more common approach is to treat payment as part of the order conversion system, while coordinating the website architecture, checkout process, multilingual pages, and marketing delivery rhythm for design.
In actual use, why different businesses have different payment integration priorities
The same cross-border e-commerce payment integration does not mean the same focus. Low-ticket fast-moving orders and high-ticket brand orders have different concerns. The former pays more attention to payment speed and mobile success rate, while the latter values authorization stability and dispute handling capability more.
If the business covers North America and Europe, credit cards are the basic capability, and PayPal usually serves as a supplement for trust and fast settlement. Local payment methods are more suitable for improving the final mile conversion in specific countries.
If the store also undertakes SEO customer acquisition tasks, payment access cannot only pursue the ability to receive payments. Checkout page loading speed, jump levels, mobile compatibility, and recovery design after failure all directly affect the conversion efficiency of search traffic.
For service systems like 易营宝 that cover intelligent website building, cross-border e-commerce, and overseas marketing at the same time, the value lies in considering front-end customer acquisition and back-end payment within the same growth path, rather than splitting them into systems that are isolated from each other.
In several high-frequency scenarios, the judgment methods for PayPal, credit cards, and local payment methods are not the same
When a brand independent site is just getting started, PayPal often takes the lead in building trust
The earliest concern for a new site is that users may hesitate to pay. At this time, cross-border e-commerce payment integration cannot only add credit card channels, because for unfamiliar brands in the cold start stage, the PayPal label itself can reduce concerns.
But PayPal cannot be treated as the only solution. Because some market users are more used to paying directly by card, leaving only one method may block potentially convertible orders.
For ad-driven e-commerce stores, payment success rate and risk control thresholds matter more
After traffic is driven into the site, order fluctuations are large and peaks are concentrated, so the stability of the payment interface will be quickly amplified. The key here is not how many payment methods there are, but whether authorization, capture, and callbacks can all remain error-free under high concurrency.
If the risk control model is too strict, normal orders will be mistakenly blocked; if it is too loose, it can easily bring refusals and fraud. Cross-border e-commerce payment integration needs to work in tandem with order recognition, address verification, and device judgment settings.
For e-commerce stores operating in multiple countries, local payment methods determine whether local markets can be penetrated
When a site starts covering Southeast Asia, Latin America, or parts of Europe, relying only on PayPal and credit cards makes it hard to achieve a full conversion. The meaning of local payment methods lies not in showing completeness, but in matching user habits.
Such scenarios usually pay more attention to the payment page language, currency display, tax explanation, and settlement cycle. If after local payment access is added, a complicated jump process is still required, the conversion improvement will be significantly weakened.
Under different scenarios, the demand differences for cross-border e-commerce payment integration can be viewed this way
To avoid treating similar businesses as the same payment demand, before landing you can first make judgments from the following dimensions.
Before landing, what really needs to be watched closely is not just whether it can be connected
Many projects, when doing cross-border e-commerce payment integration, tend to focus on the interface documents and signing process, but after going online they only discover that the problems are in the checkout experience and business coordination.
- Interface stability: whether peak periods are prone to timeouts, whether asynchronous callbacks are complete, and whether order status can be automatically corrected.
- Compliance and security: whether it supports sensitive information isolation, risk control review, verification processes, and refund traceability.
- Settlement experience: whether currency conversion is clear, whether handling fees are controllable, and whether the settlement cycle affects cash flow arrangements.
- System scalability: whether large-scale reconstruction is needed when adding new countries, local payment methods, or backup channels later.
In practical applications, the website system and payment system are best to use a unified data structure. Otherwise, the marketing side sees clicks and add-to-carts, while the payment side sees failures and disputes, making it difficult to form a complete optimization loop.
Common misjudgments often occur in these seemingly similar choices
A common misjudgment is to treat “the more payment methods, the better” as a principle. In fact, too many methods will lengthen the decision path, especially on mobile, and instead increase traffic loss.
Another misjudgment is to only look at channel fees and not consider chargeback handling, refund efficiency, and technical maintenance costs. Short-term savings may seem good, but in the long run they may be offset by disputed orders and manual review.
There is also a situation where the North American site, European site, and Southeast Asian site are all using the same payment strategy. Regional differences, device habits, tax display, and local trust structures are all different and cannot simply be reused.
If the store also undertakes SEO and ad conversion tasks, then it is even more important not to ignore checkout page speed. Too many payment jumps, overly heavy scripts, and mobile anomalies will all cause the front-end customer acquisition cost to rise passively.
A more stable cross-border e-commerce payment integration is usually advanced in phases
A more stable approach is to first establish a basic payment framework and then gradually expand local payment methods. In the first stage, ensure that PayPal and credit cards work smoothly, and connect ordering, callbacks, refunds, and reconciliation.
In the second stage, combine actual traffic sources and the proportion of orders by country to add local payment methods in key markets. This can both control implementation complexity and make it easier to see which method truly brings conversion improvement.
For businesses that are simultaneously doing multilingual sites, SEO optimization, and ad placement, the payment module is best left with flexible configuration capabilities. Different sites, currencies, regions, and promotional activities often require different payment display strategies.
This is also where the real value of an integrated platform lies. Systems like 易营宝 that cover website building, e-commerce, marketing, and optimization are more suitable for embedding payment capability into the overall growth process, rather than being repaired manually for a long time after a single-point integration.
When starting the evaluation, you can first sort out these few things clearly
Back to the question of “how to do cross-border e-commerce payment integration,” the core is not to connect interfaces according to a checklist, but to first clarify the business coverage region, main traffic sources, customer price structure, and subsequent expansion plan.
Then look at whether PayPal can serve as a trust entry point, whether credit cards can function as the basic transaction capability, and whether local payment methods are used to break through key countries. Once the judgment order is clear, the technical solution will be more stable.
A more specific way to advance is to first sort out the target markets and currencies, then verify the checkout process, risk control rules, refund mechanisms, and data callback requirements, and finally evaluate the implementation cycle, maintenance costs, and room for subsequent expansion.
In this way, cross-border e-commerce payment integration is not just a payment module, but a truly measurable and optimizable part of the independent site growth system.
Related Articles
Related Products
 Yiyingbao SaaS Intelligent Website Building and Marketing SystemYiyingbao SaaS Intelligent Website Building and Marketing System, AI-powered no-code website building, rapid creation of multilingual B2B international websites in 10 minutes, global server acceleration, AI-powered SEO optimization, helping businesses connect efficiently with global markets. The perfect integration of technology and operation makes building an international trade website remarkably simple
 AI+SEM Intelligent Advertising Marketing SystemAI+SEM drives intelligent ad creation, empowering full-funnel precision advertising marketing. The system automatically generates weekly/monthly reports, AI recommends keywords and target countries, monitors core metrics in real-time with intelligent alerts, and enables one-click high-conversion ad solutions to help quickly acquire customers and improve ROI.
 AI+SEO Dual-Engine System Optimization ServicesYiyingbao’s AI+SEO dual-engine optimization system helps foreign trade enterprises acquire high-quality organic traffic through AI-powered keyword research, content generation, and comprehensive technical optimization, significantly improving search rankings and conversion rates.
 AI+SNS Social Media Marketing SystemYingbao AI+SNS Social Media Marketing System - Precision social capture for the social media era. Supports one-click content synchronization across major platforms like Facebook and LinkedIn. AI intelligently rewrites posts for enhanced relevance. 24/7 AI customer service and user profiling analysis empower businesses to efficiently expand into global markets.
 AI+SEO营销解决方案易营宝AI+SEO营销解决方案,通过AI批量写作、智能生成TDK、精准关键词扩词等功能,全面优化网站SEO效果,提升流量与转化率。助力企业构建高效智能网站新生态。
 AI+SEM Advertising Marketing SolutionsAI+SEM Advertising Marketing Solution leverages AI technology to deeply empower SEM ad campaigns. It automatically generates weekly/monthly reports using AI, presenting account data across multiple dimensions for comprehensive insights into campaign performance and trends. The system precisely recommends keywords and target countries, intelligently generates high-conversion ad copy, and enables one-click activation of efficient campaign plans to help businesses rapidly acquire customers. Simultaneously, it monitors core metrics in real time, intelligently identifies abnormal fluctuations, and issues timely alerts to ensure stable, high-return advertising results.
 Domain Name ServicesEasyWin provides professional domain name services, including intelligent queries, one-stop registration, brand protection, and full lifecycle management, helping businesses build a digital brand image.
 EasyOperate B2C Cross-Border E-Commerce Platform & Independent WebsiteEasyStore B2C Cross-border E-commerce Independent Store is an intelligent website building and cross-border e-commerce integrated solution independently developed by EasyStore Information Technology (Beijing) Co., Ltd. The system is specially designed for small and medium-sized as well as large export enterprises, integrating 'website building, operation, marketing, advertising, and conversion' into one, helping enterprises quickly establish cross-border e-commerce independent stores to achieve brand globalization and global sales growth.
The platform supports multiple languages, multiple currencies, and multi-channel marketing, with built-in AI intelligent translation and SEO optimization systems, suitable for mainstream markets such as Southeast Asia, Europe and America, Latin America, and the Middle East, assisting Chinese manufacturing enterprises in efficiently deploying international e-commerce strategies. SSL证书易营宝提供专业SSL安全证书服务,包括单域名和泛域名证书,确保网站数据传输加密、身份验证和完整性保护,助力企业建立安全可信的在线业务环境。









