- Can the average annual growth rate reflect real opportunities in overseas markets?Oct 07, 2026View details
- Which customer acquisition channels will be affected by cross-border marketing trends in 2026?Sep 06, 2026View details
- Which homogenization risks should be considered in an analysis of the AI-powered website building industry?Aug 30, 2026View details
- How Will AI Marketing Trends 2026 Change Advertising Budget AllocationAug 28, 2026View details
- Is the EV SSL certificate market shrinking or upgrading? How should companies assess certificate procurement?Aug 11, 2026View details
- Why the old AMP SEO 2020 practices no longer work and what has changed in current optimization prioritiesAug 02, 2026View details
What Determines Facebook Advertising Costs? Budget Estimation and Cost Reduction Methods
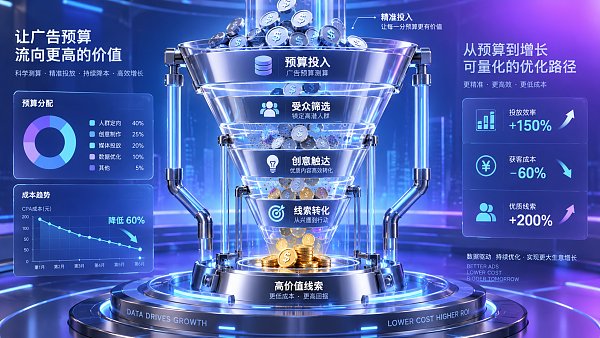
When an advertising account is ready for renewal, finance teams often ask two questions: Why does the same budget generate fewer leads this month? How much should be approved for the next round to avoid spending money on ineffective impressions? Facebook advertising does not have a single fixed “unit price.” Facebook advertising costs are essentially determined by the bidding environment, audience value, creative performance, conversion path, and campaign management approach. When approving a budget, do not look only at the cost per click or cost per lead; assess which stage of the funnel is driving the cost change.
A more prudent approach is to first determine the customer acquisition cost the business can afford, then work backward to define the testing budget and scaling limit. Expensive impressions do not necessarily mean a campaign has failed: high-value markets, highly competitive audiences, or audiences with stronger purchase intent are generally more expensive by nature. What truly requires attention is when costs rise while click-through rate, landing page conversion rate, and qualified lead rate continue to decline.
Break Down Costs First: Where Is the Money Actually Going?
Facebook ads use an auction mechanism, and actual spend is not determined by bids alone. The system considers signals such as the amount an advertiser is willing to pay, the likelihood of users taking action, and ad quality to determine impression opportunities. Therefore, budget approval should not directly equate “daily budget” with “estimated customer acquisition volume”; there are at least several stages in between, including impressions, clicks, visits, submissions, and sales confirmation.
Among these, the final stage is the most suitable for approval decisions. Calculating based only on form submissions can lead teams to favor low-cost, low-intent traffic; looking only at closed deals can prevent timely adjustments due to the long sales cycle. In practice, both “lead cost on the ad platform” and “qualified lead cost after sales confirmation” can be retained, with the calculation periods for both clearly defined.
Which Factors Increase Budgets, and Which Are Normal Fluctuations?
When entering a new market, initial costs are usually unstable. The account lacks historical conversion signals, while audiences, creatives, and landing pages are still being tested, and the system needs time to accumulate feedback. Rejecting a channel based on first-week costs too early can easily mean missing effective combinations. However, if campaigns have been running for some time and costs suddenly rise, investigate in the following order.
- Whether the audience is too narrow or repeatedly reached. Excessive targeting conditions can reduce the available bidding audience; when multiple ad sets target similar audiences, internal competition may also occur. Continuously increasing frequency and declining click-through rates often indicate creative fatigue or that the audience is nearing saturation.
- Whether creatives are disconnected from the target market. Product selling points, language, and calls to action in images, short videos, and copy should align with the comprehension habits of local users. If creative assets cannot generate clicks, subsequent page optimization will be difficult to compensate for.
- Whether the optimization objective aligns with the business objective. When the goal is traffic, the system seeks people more likely to click; when the goal is form submissions, it seeks people more likely to submit. The price and quality of these two types of traffic differ, so the lower cost of the former cannot be directly treated as a customer acquisition advantage.
- Whether conversion follow-through is interrupted. Inconsistency between the ad promise and the above-the-fold page message, slow page loading, and difficult-to-complete mobile forms all leave cost pressure on the advertising side. Increasing the budget in this situation will only amplify waste.
- Whether external competition has changed. Promotional seasons, periods of concentrated industry promotion, or intensified bidding in popular regions may raise impression costs. Such fluctuations may not be entirely avoidable, but risks can be spread through combinations of regions, time periods, and creatives.
A Budget Is Not Just a Number to Approve; It Should Be Derived from Affordable Customer Acquisition Costs
Before approval, first confirm with the sales team or business owner: after a qualified lead enters follow-up, what is the maximum marketing cost that can be invested? Then, based on historical data or phased targets, estimate the approximate conversion rates from click to submission and from submission to qualified lead. Without sufficient historical data, the initial budget should be defined as a “validation budget,” rather than directly committing to customer acquisition at scale.
For example, budget calculations can follow this logic: first set the upper limit for qualified lead cost, then calculate the allowable form cost based on the qualification rate; calculate the affordable click cost based on the landing page conversion rate; and finally arrange the testing period based on expected click volume. Each stage should retain a reasonable buffer to avoid misjudging ad performance because of delayed sales follow-up, attribution window differences, or short-term bidding fluctuations.
During the testing phase, budgets should not be split into too many small portions. If there are too many ad sets and each has insufficient spend, it becomes difficult to determine whether differences are caused by audiences, creatives, or pages. A more practical arrangement is to retain a limited number of core audience combinations while testing a small number of clearly differentiated creatives; adjust only one main variable at a time and record changes in impressions, clicks, submissions, and qualified leads before and after each adjustment. This makes cost changes explainable.
The Focus of Cost Reduction Is Eliminating Ineffective Spend, Not Simply Lowering Bids
Directly lowering bids may reduce impressions, but it may also cause campaigns to miss high-value audiences. A more controllable path to cost reduction is to first stop clearly ineffective combinations, then shift resources toward areas with quality signals. During financial review, the campaign team can be required to provide data broken down by country or region, audience, creative, and placement, rather than reviewing only the overall account report.
- First exclude creatives with low click-through rates that have already received sufficient impressions, to avoid continuing to spend on creatives that generate little interest.
- Review ad sets with high clicks but low submissions, and prioritize correcting landing page information, loading speed, and form design.
- Distinguish between sources with “many submissions” and those with a “high qualification rate.” Tighten targeting or add screening criteria for low-quality sources to prevent artificially low lead costs from concealing actual waste.
- Calculate retargeting audiences separately from first-touch audiences. The former often converts faster but has limited scale, so its cost cannot be used as a substitute for overall customer acquisition cost.
- Set pause rules for combinations that continuously exceed cost thresholds without signs of improvement, while retaining the necessary testing budget to prevent the account from being left with only old audiences.
When there are many delivery regions, creative versions, and campaigns, manual aggregation can easily result in inconsistent calculation standards. When regular reporting to management is required, the core metric monitoring, intelligent alerts, and weekly and monthly report generation functions of the AI+SEM Intelligent Advertising Marketing System can be used to review regions, keyword strategies, and campaign performance from the same data perspective. The focus of approval is not automation itself, but whether the reasons behind budget increases and decreases can be clearly identified and traceable adjustment records retained.
What Information Should Be Required During Approval?
A campaign request suitable for decision-making should at least specify the campaign objective, region and audience scope, budget period, core conversion events, cost ceiling, and pause conditions. If it only states “expand impressions” or “increase leads” without explaining how lead quality is defined and how follow-up will be conducted, it is difficult to assess the actual return on the budget.
A monthly review should consider “planned value, actual spend, conversion at each stage, qualified lead rate, causes of anomalies, and next-step adjustments” together. In this way, even if Facebook advertising costs temporarily rise, it is possible to determine whether this is a normal fluctuation caused by intensified competition or a structural issue resulting from ineffective creatives, pages, or audiences. Only when costs can be explained can they be controlled; only when advertising data is connected to business outcomes does budget approval become more than simply a judgment on a media expense.
Related Articles
Related Products
 Yiyingbao SaaS Intelligent Website Building and Marketing SystemYiyingbao SaaS Intelligent Website Building and Marketing System, AI-powered no-code website building, rapid creation of multilingual B2B international websites in 10 minutes, global server acceleration, AI-powered SEO optimization, helping businesses connect efficiently with global markets. The perfect integration of technology and operation makes building an international trade website remarkably simple
 AI+SEM Intelligent Advertising Marketing SystemAI+SEM drives intelligent ad creation, empowering full-funnel precision advertising marketing. The system automatically generates weekly/monthly reports, AI recommends keywords and target countries, monitors core metrics in real-time with intelligent alerts, and enables one-click high-conversion ad solutions to help quickly acquire customers and improve ROI.
 AI+SEO Dual-Engine System Optimization ServicesYiyingbao’s AI+SEO dual-engine optimization system helps foreign trade enterprises acquire high-quality organic traffic through AI-powered keyword research, content generation, and comprehensive technical optimization, significantly improving search rankings and conversion rates.
 AI+SNS Social Media Marketing SystemYingbao AI+SNS Social Media Marketing System - Precision social capture for the social media era. Supports one-click content synchronization across major platforms like Facebook and LinkedIn. AI intelligently rewrites posts for enhanced relevance. 24/7 AI customer service and user profiling analysis empower businesses to efficiently expand into global markets.
 AI+SEO营销解决方案易营宝AI+SEO营销解决方案,通过AI批量写作、智能生成TDK、精准关键词扩词等功能,全面优化网站SEO效果,提升流量与转化率。助力企业构建高效智能网站新生态。
 AI+SEM Advertising Marketing SolutionsAI+SEM Advertising Marketing Solution leverages AI technology to deeply empower SEM ad campaigns. It automatically generates weekly/monthly reports using AI, presenting account data across multiple dimensions for comprehensive insights into campaign performance and trends. The system precisely recommends keywords and target countries, intelligently generates high-conversion ad copy, and enables one-click activation of efficient campaign plans to help businesses rapidly acquire customers. Simultaneously, it monitors core metrics in real time, intelligently identifies abnormal fluctuations, and issues timely alerts to ensure stable, high-return advertising results.
 Domain Name ServicesEasyWin provides professional domain name services, including intelligent queries, one-stop registration, brand protection, and full lifecycle management, helping businesses build a digital brand image.
 EasyOperate B2C Cross-Border E-Commerce Platform & Independent WebsiteEasyStore B2C Cross-border E-commerce Independent Store is an intelligent website building and cross-border e-commerce integrated solution independently developed by EasyStore Information Technology (Beijing) Co., Ltd. The system is specially designed for small and medium-sized as well as large export enterprises, integrating 'website building, operation, marketing, advertising, and conversion' into one, helping enterprises quickly establish cross-border e-commerce independent stores to achieve brand globalization and global sales growth.
The platform supports multiple languages, multiple currencies, and multi-channel marketing, with built-in AI intelligent translation and SEO optimization systems, suitable for mainstream markets such as Southeast Asia, Europe and America, Latin America, and the Middle East, assisting Chinese manufacturing enterprises in efficiently deploying international e-commerce strategies. SSL证书易营宝提供专业SSL安全证书服务,包括单域名和泛域名证书,确保网站数据传输加密、身份验证和完整性保护,助力企业建立安全可信的在线业务环境。